Home | Insights | European Hotels Update H1 2024

European Hotels Update H1 2024

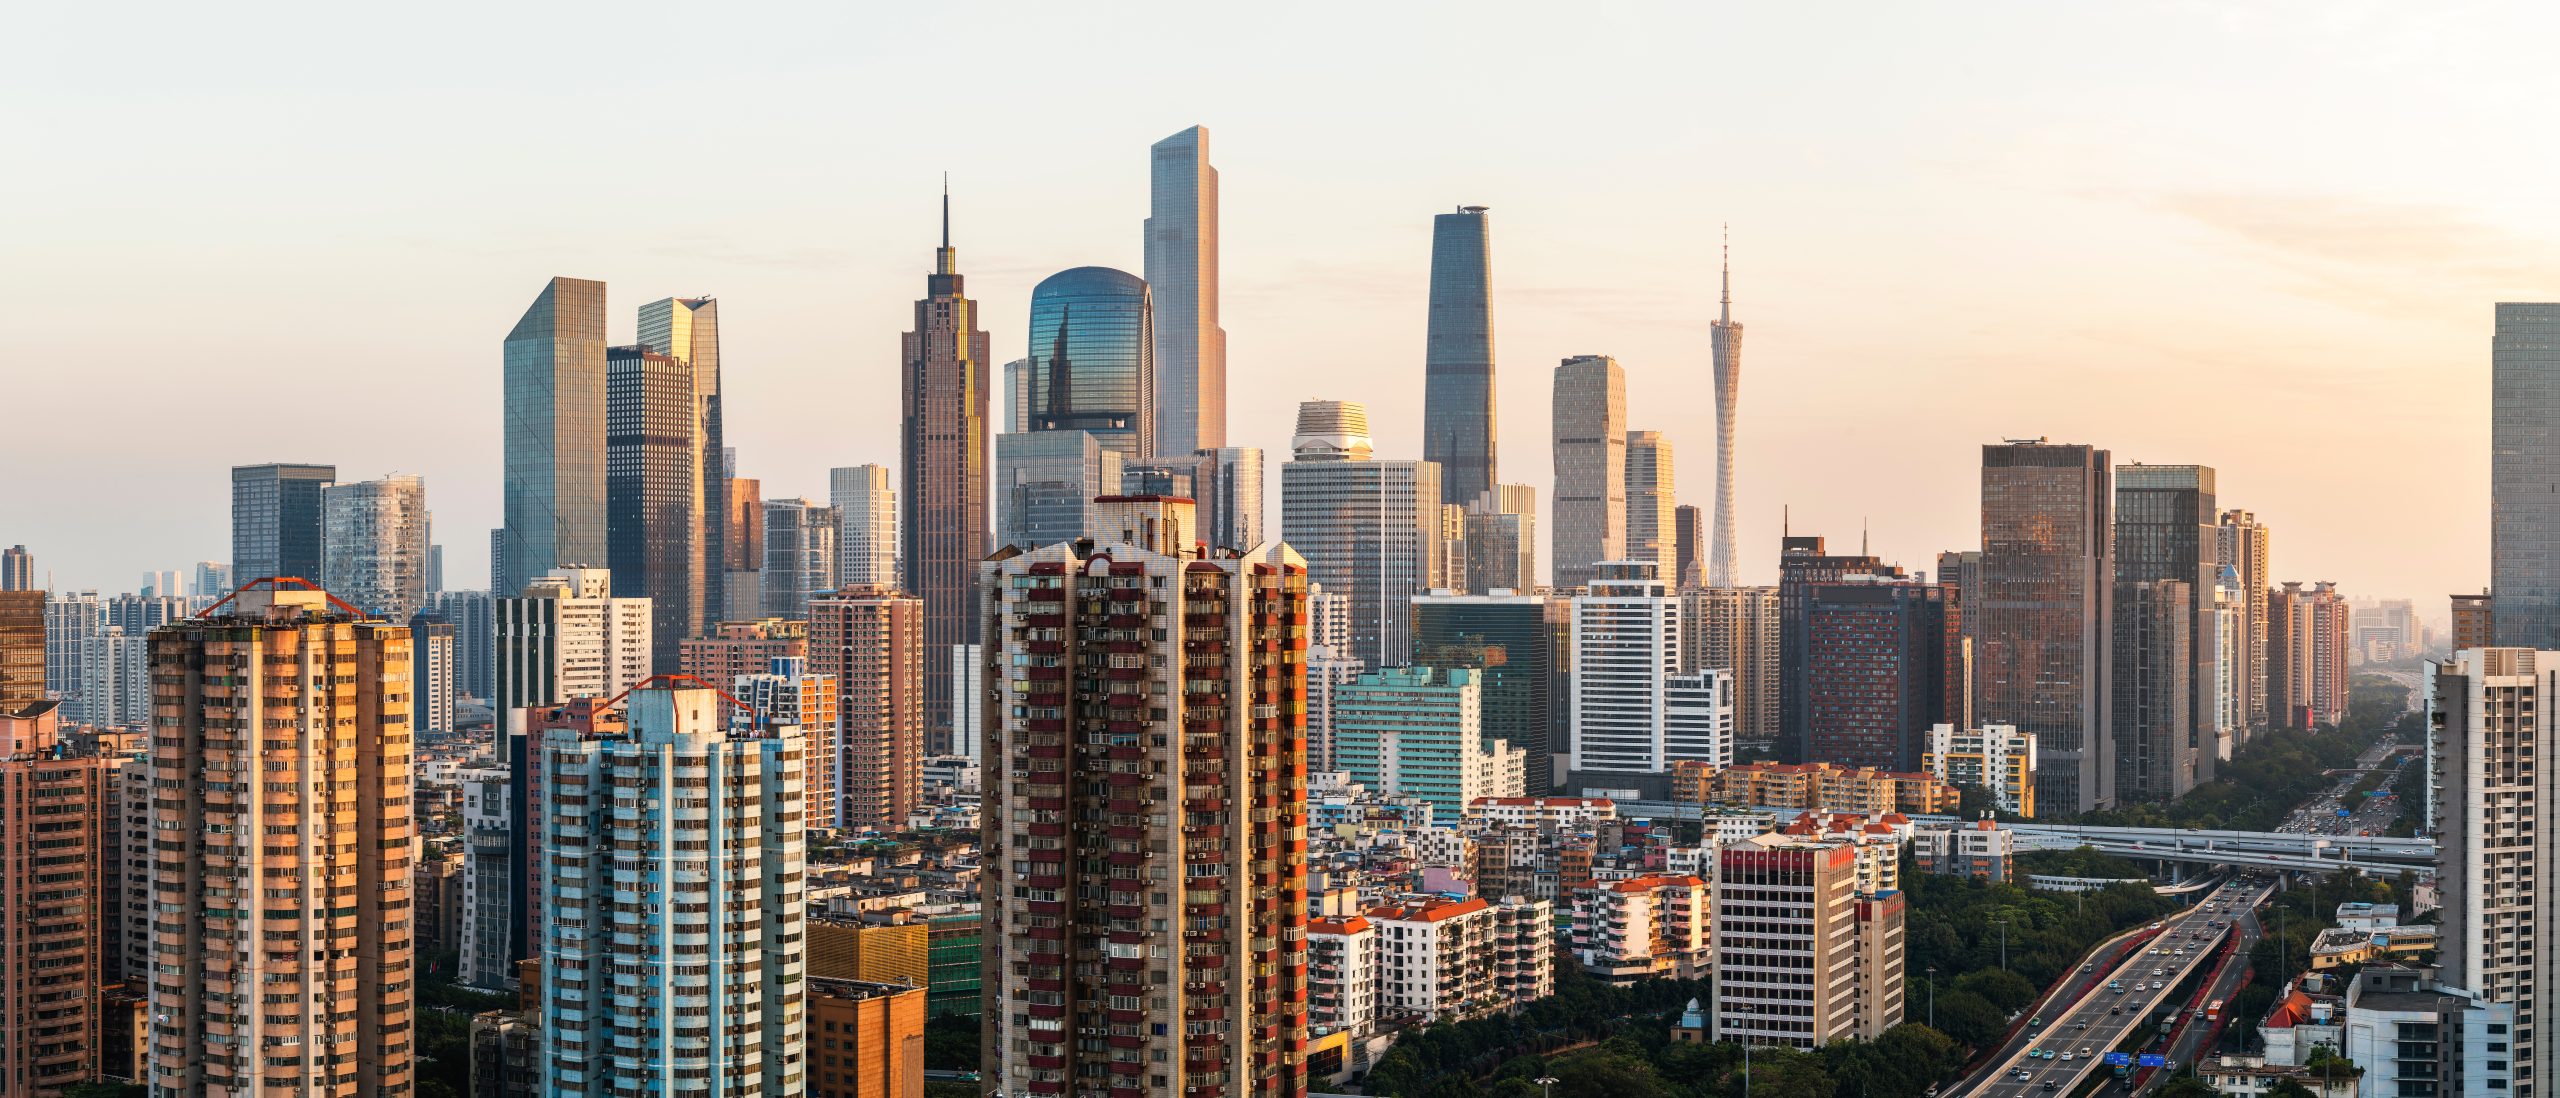
In H1 2024, European hotel demand surged 12% above pre-pandemic levels, with profitability improving in major cities like London and Barcelona. RevPAR rose by 5% over 2023 and 26% over 2019, driven by ADR growth and occupancy recovery. Nearly half of the €11.6 billion in investment focused on luxury and upper-upscale hotels, while yields remained stable, with slight declines across Europe and the UK.

OTHER INSIGHTS

Future Flows

Discover how two global forces – Europe’s defence build-up and the expansion of Chinese businesses into Europe – are reshaping demand for industrial and logistics real estate. Cushman & Wakefield’s “F...

Read more
CEE Retail Marketbeat Q2 2026

Retail markets across CEE-6 continued to favor tenants able to secure efficient units in dominant, high-footfall schemes, while landlords in supply-constrained prime high streets retained stronger pri...

Read more

CEE Office Marketbeat Q2 2026

Within a broader European context, occupier conditions across CEE-6 capitals remain predominantly landlord-favourable, with Prague, Warsaw, Bratislava, and Sofia all characterized by demand outstrippi...

Read more
Privacy Overview

This website uses cookies so that we can provide you with the best user experience possible. Cookie information is stored in your browser and performs functions such as recognising you when you return to our website and helping our team to understand which sections of the website you find most interesting and useful.

Strictly Necessary Cookies

Strictly Necessary Cookie should be enabled at all times so that we can save your preferences for cookie settings.

3rd Party Cookies

This website uses Google Analytics to collect anonymous information such as the number of visitors to the site, and the most popular pages.

Keeping this cookie enabled helps us to improve our website.