Future Flows
Bucharest, September 2026: Bucharest’s hotel market recorded a strong performance in H1 2026, with revenue per available room (RevPAR) in EUR increasing by 5% and 25.2% compared to H1 2025 and H1 2019 pre-pandemic levels, respectively.
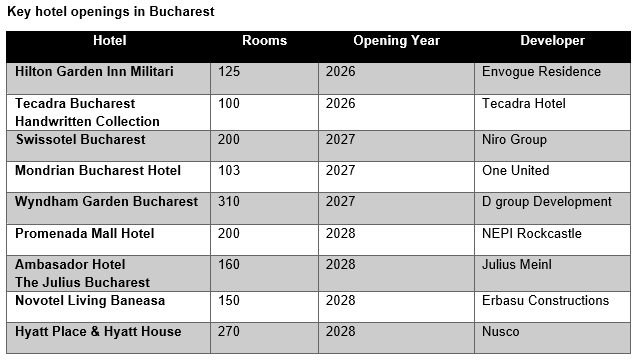
This strong market performance encourages further interest in new hotel developments. By 2028, the pipeline is expected to add more than 1,500 rooms to the existing hotel stock, representing a significant increase in supply across all segments, from midscale to luxury properties, equivalent to approximately 13.0% of the existing hotel stock.
Among the projects announced for delivery over the next three years are Swissotel Bucharest (199 rooms), Hyatt House and Hyatt Place Nusco City Bucharest (270 rooms), Ambasador Hotel The Julius Bucharest (160 rooms), and Promenada Mall Hotel (205 rooms).
Two major openings are scheduled for 2026 – Hilton Garden Inn Militari and Tecadra Bucharest Handwritten Collection, adding a total of 225 rooms to the market.
One of the most recent hotel openings was the Mercure Bucharest Cantemir, a 40-room Upscale property located within walking distance of Unirii Square, the Old Town, and Tineretului Park.
The CEE-6 region recorded an 8.2% year-over-year increase in RevPAR (in EUR) in H1 2026, supported by a 4.7% uplift in ADR (in EUR) and a 2.1 pp. rise in occupancy.
Growth was particularly notable in Bulgaria, the Czech Republic, Hungary, and Slovakia, all recording double-digit RevPAR gains compared to the same period last year. At city level, Budapest (15.3%), Bratislava (13.5%) and Prague (10.5%) posted the strongest RevPAR growth in H1 2026 compared to H1 2025.
Compared to H1 2019, the pre-pandemic benchmark year, Bucharest hotel RevPAR (in EUR) in H1 2026 is 25.2% higher. In the same timeframe, ADR (in EUR) surpassed pre-pandemic levels by 27.7%, while occupancy rates remain slightly below 2019 levels, but the gap has narrowed to 2.0%.
The year-over-year growth was mainly driven by a 3.2% increase in ADR (in EUR), while occupancy grew by 1.9%.
Bucharest recorded EUR 46.3 million in hotel investment volume in 2025. This represents an increase of c. 182.0% versus the transaction volume achieved in 2024. According to our database, this investment volume was generated by 3 transactions (i.e. Hotel Duke 2-asset portfolio and Hilton Garden Inn Bucharest Airport). The transacted properties are positioned in the Upper Midscale, Midscale, and Upscale segments.
Hotel investment activity across the CEE-6 region remained strong in H1 2026, with transaction volume exceeding the figures recorded during the five years preceding 2025. More than half of transactions in H1 2026 involved midscale properties, marking a shift from H1 2025, when upper-upscale assets were the most actively traded segment.
Alina Cazachevici MRICS, Partner, Head of Valuation & Advisory, Hospitality & Alternatives, CEE/SEE at Cushman & Wakefield: “Robust hotel performance continues to attract both local and international investors, who increasingly recognize the growth potential of the Bucharest market. Nevertheless, investors continue to navigate a challenging environment characterized by political uncertainty, fiscal tightening, and a softer economic outlook, all of which are weighing on confidence and pricing expectations. As across much of the CEE region, transaction activity remains largely driven by regional capital, while international investors remain selective, focusing primarily on prime assets offering resilient cash flows and strong long-term return potential.”
In 2025, Bucharest, Budapest, and Prague recorded mild yield compressions of 25 bps, while in H1 2026, yields in the CEE-6 region remained unchanged. The market continues to see strong macroeconomic fundamentals, such as moderate inflation and a stronger and more competitive financing environment, alongside strengthening domestic capital, which continues to support capital inflows across the region.
Elena Osain, Analyst, Valuation & Advisory, Hospitality & Alternatives, CEE/SEE at Cushman & Wakefield: “Bucharest’s hotel market continues to outperform, with total tourist overnights in 2026 expected to increase over 8.0% year-on-year according to Oxford Economics, with both local and international overnights exceeding pre-pandemic levels. H1 2026, RevPAR surpassed pre-pandemic levels by 25.2%, driven by strong ADR growth and reflecting hotels’ increasing focus on a rate-driven strategy.”