Bucharest Flex Office Overview 2026
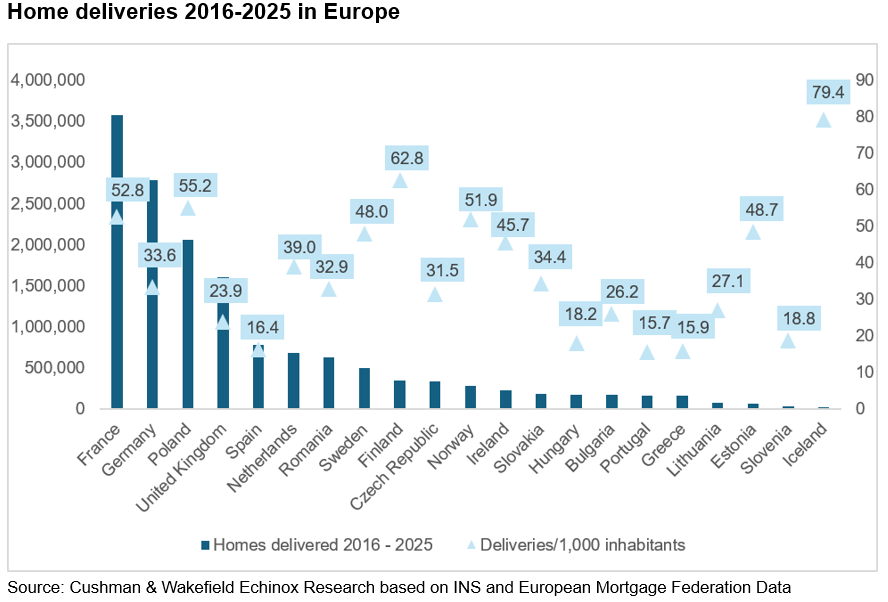
Bucharest, October 2026: More than 636,000 homes were completed in Romania between 2016 and 2025, equivalent to almost 33 new homes per 1,000 inhabitants, according to an analysis by Cushman & Wakefield Echinox based on housing completion data compiled for the 2016-2025 period. These figures place Romania broadly in the middle of the 21 European markets included in the analysis, close to Germany, Slovakia and Czechia, while significantly ahead of Hungary, Spain and Portugal in terms of housing deliveries relative to population.
Romania recorded 32.9 completed homes/1,000 inhabitants during the analyzed decade. This compares with 33.6 in Germany, 34.4 in Slovakia and 31.5 in Czechia.
Residential construction intensity was considerably higher in markets such as Poland, with 55.2 homes/1,000 inhabitants, France (52.8), Finland (62.8) and the Netherlands (39).
At the other end of the spectrum, the indicator stood at 26.2 in Bulgaria, 23.9 in the United Kingdom, 18.2 in Hungary, 16.4 in Spain and 15.7 in Portugal.
In absolute terms, 636,310 homes were completed in Romania between 2016 and 2025 according to the National Institute of Statistics. Annual deliveries increased from 52,200 units in 2016 to a peak of 73,300 units in 2022. Subsequently, the market entered a downward phase, with completions falling to 71,000 homes in 2023, 61,000 in 2024 and 59,000 in 2025.
Consequently, the 2025 volume was ~19.5% below the 2022 peak, but still 13% above the 2016 level.
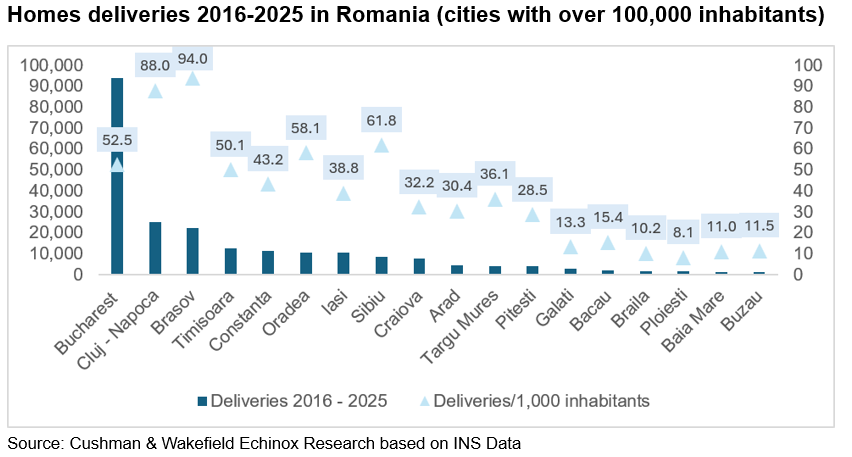
The differences between Romania’s main cities (those with a population exceeding 100,000 inhabitants) are even more pronounced. Bucharest was by far the country’s largest residential market in absolute terms, with 93,850 homes completed between 2016 and 2025, compared with 25,200 in Cluj-Napoca and 22,300 in Brasov.
However, a different picture emerges when deliveries are connected to the population size. Brasov leads the major cities included in the analysis, with 94 completed homes/1,000 inhabitants during the decade, followed by Cluj-Napoca with 88. Sibiu recorded 61.8 homes/1,000 inhabitants, Oradea 58.1, while Bucharest reached 52.5. Timisoara came close to the capital city, with 50.1 homes/1,000 inhabitants.
Below these levels were Constanta, at 43.2 homes/1,000 inhabitants, Iasi (38.8), Targu Mures (36.1) and Craiova at 32.2. At the lower end of the ranking, Ploiesti recorded just 8.1 completed homes/1,000 inhabitants, Braila 10.2, Baia Mare 11 and Buzau 11.5 during the analyzed period.
The data therefore points to a highly polarized residential development landscape, in which the size of a city does not necessarily translate into a proportionally larger new housing supply.
The recent figures also suggest that Romania has moved beyond the exceptionally strong residential delivery cycle recorded at the beginning of this decade. Following the peak of 73,300 completed homes in 2022, national deliveries decreased by 3.2% in 2023, by a further 14.1% in 2024 and by 3.1% in 2025.
The slowdown is visible in most of the country’s major residential markets. Bucharest delivered 9,361 homes in 2025, compared with a decade-high 13,834 units in 2023, representing a decline of ~32% from that peak. Despite the correction, Bucharest’s 2025 volume remained approximately 144% above the 3,838 homes completed in 2016.
The adjustment has been considerably sharper in some regional centers. Cluj-Napoca recorded 957 completions in 2025, compared with 4,175 at its 2019 peak, while Brasov delivered 1,283 homes versus a peak of 3,098 in 2020. Timisoara reached 793 completions in 2025, compared with 1,787 in 2021, and Iasi recorded 780, versus 1,908 in 2019.
 Vlad Saftoiu, Head of Research Cushman & Wakefield Echinox: “The evolution of the past decade confirms that the country’s major urban centers have become key drivers of residential development, with the capacity to support a consistent pipeline of new projects. Although deliveries have moderated since the peak of 2022, this trend reflects a market adjustment rather than a structural decline, as demand and economic growth continue to provide opportunities across the residential sector. At the same time, the analysis highlights an increasingly polarized landscape, in which the intensity of residential development varies considerably between cities and is not necessarily proportional to their size. The market is thus entering a more selective phase, in which location, accessibility, infrastructure and the adaptation of residential products to buyers’ profiles and purchasing power will become decisive factors for the performance of new projects. In an environment where developers are adopting a more cautious approach, we believe that well-positioned units in markets with solid economic fundamentals, aligned with buyers’ needs and affordability, will continue to have favorable prospects.”