The CEE-6 retail sector showed moderate resilience in Q2 2025, with real retail sales up 3.5% YoY. Consumer sentiment remained cautious due to inflation (3.8%), but stable employment and record-breaking tourism supported spending. Czechia led with 4.6% retail growth, while Slovakia saw a decline of 2.1%. Consumers prioritized essentials and experiences over discretionary purchases.
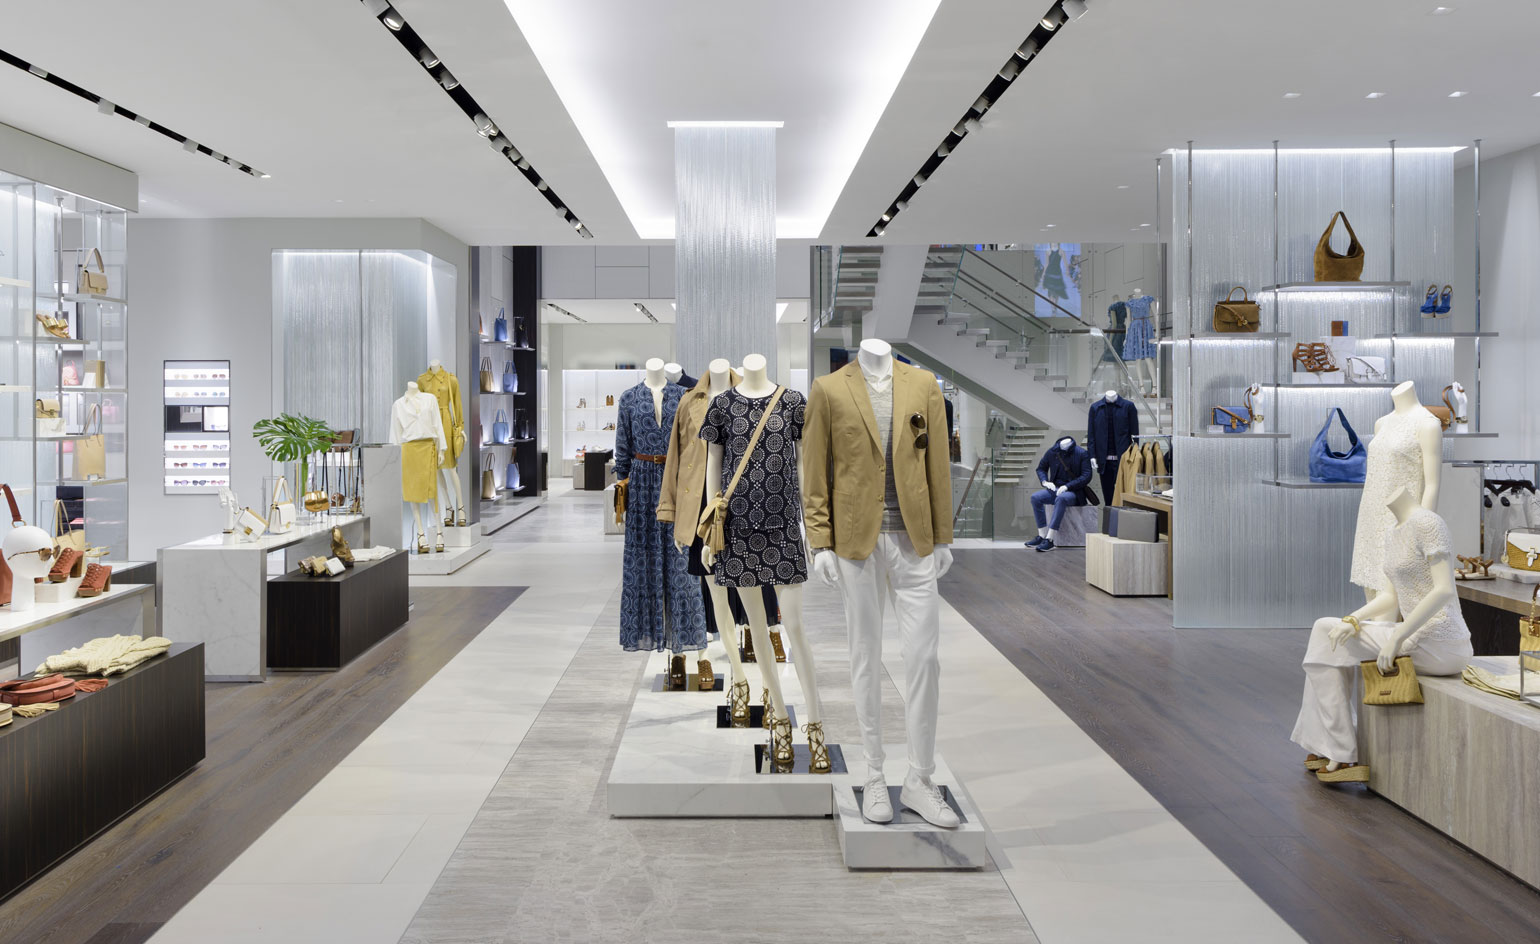
Retailers are shifting toward experiential formats and omnichannel integration, transforming flagship stores into brand destinations. Food & Beverage offerings are increasingly central to driving footfall and dwell time. Pop-up stores are used strategically for market testing and agility. Physical stores remain vital for brand presence, especially in prime urban locations.
Tenant demand remained resilient in H1 2025, led by fashion and mixed goods operators. Poland welcomed six new brands and posted 7.6% retail sales growth in April. Romania saw strong leasing driven by Mall Moldova (125,700 sq m). Bulgaria added 75 new stores, mainly in retail parks. Slovakia recorded key international debuts including Müller and Victoria’s Secret.
H1 2025 delivered 468,200 sq m of new retail space, with retail parks accounting for 57%. Total retail park stock reached 9.4 million sq m (+8% YoY). Shopping centre pipeline contracted to 192,100 sq m, with no active projects in Slovakia or Bulgaria. Retail park development remains strong, with 929,700 sq m under construction, 51% of which is in Poland.
Prime rents continued to rise, especially in retail parks and high streets, supported by limited availability and tourism. Poland led with 12–13% YoY growth. However, landlords are offering more incentives—such as rent-free periods and fit-out contributions—compressing effective rental rates.
Outlook
• Retailers will continue transforming key stores into experiential destinations, supported by pop-up formats and strong F&B offerings.
• Tourism growth will sustain high street performance, especially in Prague, Kraków, and Budapest.
• New brand entries will focus on capital cities and established retail hubs, with fashion and mixed goods leading.
• Landlords prioritize refurbishments and ESG upgrades to attract premium tenants and remain competitive.